
Macro Regimes Analysis
Pricing
Pay per usage
Macro Regimes Analysis
Macroeconomic regime classification engine identifying economic cycle phases (Reflation, Inflation, Stagflation, Deflation). Key Capabilities: Copper / Gold Ratio: Leading global economic growth and industrial demand barometer. Yield Curve Regimes: US 10-Year and 30-Year Treasury yield dynamics.
Pricing
Pay per usage
Rating
0.0
(0)
Developer
khalid naami
Maintained by CommunityActor stats
1
Bookmarked
2
Total users
1
Monthly active users
23 days ago
Last modified
Categories
Share
Cross-Asset Macro Regimes & Yield Premium Intelligence Actor
Institutional-grade quantitative macro model analyzing the Copper/Gold Growth Proxy Ratio, 10-Year & 30-Year Treasury Yield Regimes, OLS Linear Regression Implied Yields, Term-Premium Residuals (Rich vs Cheap $bp$), and Rolling Gold Beta / Correlation Sensitivities.
🏛️ Economic Rationale & Institutional Model
-
Copper / Gold Ratio ($\frac{\text{Copper}}{\text{Gold}} \times 100$):
- Copper (Doctor Copper): Highly sensitive to global industrial production, manufacturing demand, and capital expenditures.
- Gold: The ultimate monetary store of value and safe-haven asset responding to real yields and debt sustainability risks.
- The Ratio: Represents the global benchmark for macroeconomic expansion vs risk-off deflationary pressure.
-
10Y Yield OLS Regression & Term Premium:
- Linear regression of US 10-Year Benchmark Yields against the Copper/Gold Ratio over 1-Year and 2-Year rolling windows: $$\text{Implied } 10\text{Y Yield} = \alpha + \beta \cdot \left(\frac{\text{Copper}}{\text{Gold}} \times 100\right)$$
- Residual (Term Premium Spread):
$$\text{Residual } (bp) = \left(Y_{10\text{Y, Actual}} - Y_{10\text{Y, Implied}}\right) \times 100\text{ bp}$$
- Rich / Term Premium Surplus ($> +15\text{ bp}$): Long-end yields are elevated above growth fundamentals (supply/deficit pressures, fiscal risk, or rate persistence).
- Cheap / Growth Discount ($< -15\text{ bp}$): Yields are depressed relative to commodity growth signals (flight-to-quality or safe-haven demand).
- Fundamental Alignment: Market rates are trading in fair-value equilibrium with global industrial demand.
-
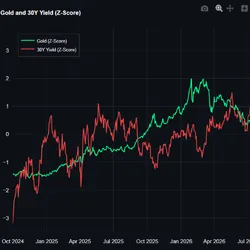
Gold Beta & Correlation to 30Y Treasury Yields:
- Evaluates gold's sensitivity to shifts in long-term discount rates: $$\beta_{\text{Gold}, 60d} = \frac{\text{Cov}(\Delta % \text{Gold}, \Delta bp Y_{30})}{\text{Var}(\Delta bp Y_{30})}$$
- Rates-Reactor Mode ($\beta < -0.04$): Standard monetary policy reaction (gold drops when long yields surge).
- Stagflation / Fiscal Credibility Hedge ($\beta > +0.02$): Gold decouples from rates, rising alongside yields as an inflation and debt hedge.
📥 Input Parameters
| Parameter | Type | Default | Description |
|---|---|---|---|
period | String | "2y" | Lookback window for regression and Z-score calculations (1y, 2y, 3y, 5y, 10y). |
goldSymbol | String | "GC=F" | Gold ticker (Futures GC=F or ETF GLD). |
copperSymbol | String | "HG=F" | Copper ticker (Futures HG=F or ETF CPER). |
includeHistoricalTimeSeries | Boolean | true | Include full daily historical dataset records. |
📤 Output Structure
1. Default Dataset (Daily Overview)
2. Key-Value Store (OUTPUT)
Comprehensive JSON report with:
currentRegimeSummary: Latest snapshot, ratio percentile, yield spreads, and regime classifications.regressionModels: 1-Year and 2-Year OLS regression formulas, slopes, intercepts, and $R^2$ goodness of fit.automatedMacroNarrative: Dynamic institutional commentary.
🎯 Institutional Use Cases
- Asset Allocation & Fixed Income Positioning: Identify when 10Y/30Y Treasuries are mispriced relative to global physical commodity demand.
- Commodity & Precious Metals Trading: Detect regime shifts where Gold transitions from a rates-sensitive asset to a fiscal debasement hedge.
- Cross-Asset Macro Hedge Funds: Systematic factor inputs for global macro models and risk parity portfolios.


