
UK Gilt Yields & Bank Rate Daily Panel with GBP FX
Pricing
from $0.50 / 1,000 results
UK Gilt Yields & Bank Rate Daily Panel with GBP FX
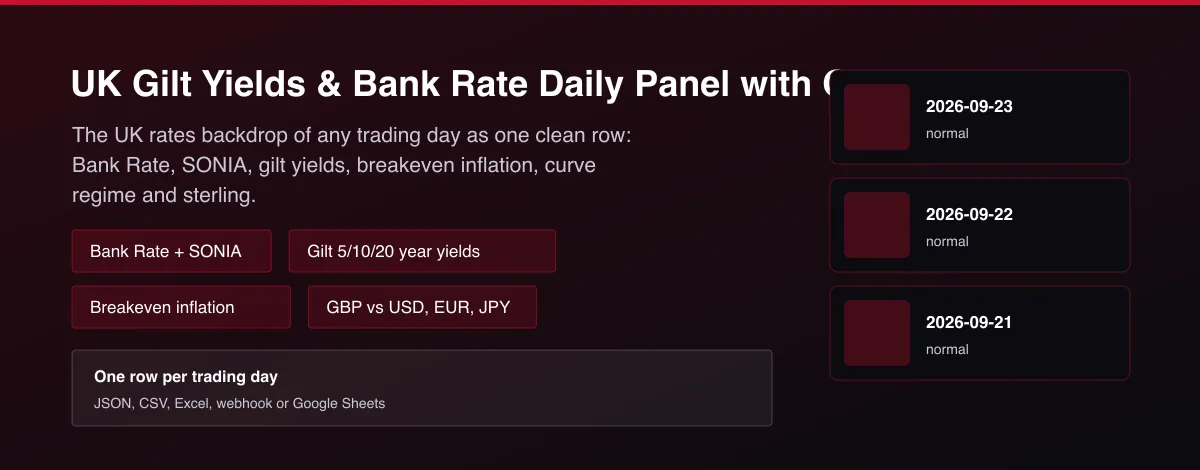
Daily UK rates panel from the Bank of England: Bank Rate, SONIA, 5, 10 and 20 year gilt yields, real yield and breakeven inflation, curve spreads, changes, percentiles and GBP exchange rates in one row per day.
What does UK Gilt Yields & Bank Rate Daily Panel with GBP FX do?
UK Gilt Yields & Bank Rate Panel returns one row per UK business day with the rates backdrop that market predictors, macro dashboards and risk models use. Each row holds the Bank of England Bank Rate, SONIA, the 5, 10 and 20 year nominal gilt par yields, the 10 year zero-coupon nominal and real yields with the implied breakeven inflation rate, the 10s5s and 20s5s curve spreads in basis points with a curve regime label, the gap between the 10 year gilt and Bank Rate, daily changes, the 1-year percentile of the 10 year gilt and the sterling exchange rates against the US dollar, euro and yen. All data is published by the Bank of England.
Why use UK Gilt Yields & Bank Rate Daily Panel with GBP FX?
- Ready to join: one row per date, so it merges with any price or return series on the date.
- Derived features included: spreads, breakeven, changes, percentiles and a curve regime label.
- Official source: the Bank of England statistical database.
- Sterling FX from the same source, so rates and currency line up on the same dates.
- Bulk history in one run or a daily delta of only the new day. No API key or login.
What makes this different
UK rate data usually means navigating the Bank of England database series by series and writing your own spreads and percentiles. This Actor selects the right series, joins them by date and computes the features once, so your model gets the UK backdrop in one table.
Who can use the UK Gilt Yields & Bank Rate Panel and how?
- Quant researchers: add UK rates and sterling features to price and return models.
- Portfolio managers: monitor gilt curve shape and yield levels.
- Mortgage and rates analysts: track gilt yields and Bank Rate together, a common driver of fixed mortgage pricing.
- Economists and students: study the UK yield curve, breakeven inflation and sterling together.
- Newsletter writers: publish a daily UK rates dashboard.
- Fintech apps: show the rates backdrop beside a UK portfolio.
- AI agent builders: let an assistant answer what gilt yields and Bank Rate are today.
- Backtesting platforms: filter historical signals by UK curve regime.
How it works
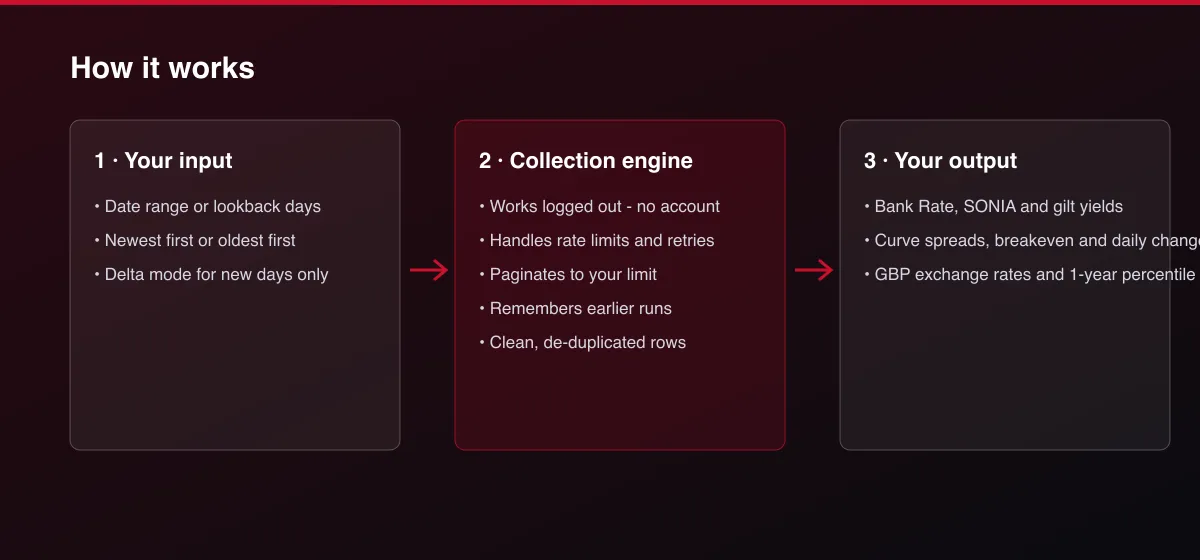
- Your input — set a date range or a lookback in days.
- The Actor collects it — the Actor reads Bank of England and joins the series by date.
- Your output — you get one row per trading day with derived features; schedule it daily with delta mode to append each new day.
What data can you extract?
The dataset has 25 fields per row:
| Field | Type | Description |
|---|---|---|
date | string | Trading date, YYYY-MM-DD. |
bank_rate | number | Bank of England Bank Rate, percent. |
sonia | number | SONIA overnight rate, percent. |
gilt_5y | number | 5 year gilt par yield, percent. |
gilt_10y | number | 10 year gilt par yield, percent. |
gilt_20y | number | 20 year gilt par yield, percent. |
gilt_10y_zero | number | 10 year nominal zero-coupon yield, percent. |
real_10y_zero | number | 10 year real zero-coupon yield, percent. |
gbp_usd | number | Sterling per US dollar rate (USD per GBP). |
gbp_eur | number | Euros per pound. |
gbp_jpy | number | Yen per pound. |
spread_10y_5y_bps | number | Yield spread 10y 5y, basis points. |
spread_20y_5y_bps | number | Yield spread 20y 5y, basis points. |
gilt_10y_over_bank_rate_bps | number | 10 year gilt yield minus Bank Rate, basis points. |
breakeven_10y | number | 10 year breakeven inflation (nominal minus real), percent. |
curve_regime | string | inverted, flat or normal. |
change_10y_bps | number | 1-day change in 10y, basis points. |
change_5y_bps | number | 1-day change in 5y, basis points. |
change_bank_rate_bps | number | 1-day change in bank rate, basis points. |
gbp_usd_change_1d_pct | number | 1-day change in gbp usd, percent. |
gilt_10y_percentile_1y | number | Percentile of gilt 10y over the last 252 trading days. |
fetch_path | string | How the data was obtained. |
source | string | Data source. |
scraped_at | string | Timestamp. |
actor_version | string | Actor version. |
How to use UK Gilt Yields & Bank Rate Daily Panel with GBP FX
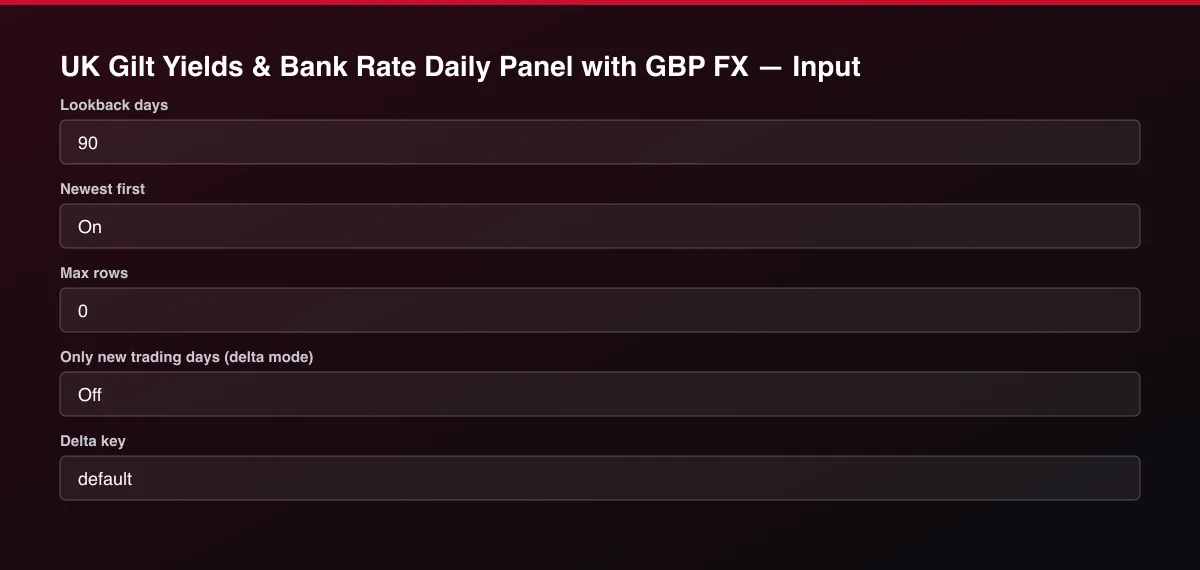
- Open the Actor and go to the Input tab.
- Leave the dates empty for the last 90 days, or set Start date and End date for a long history. Turn on Only new trading days (delta mode) and schedule the Actor after the Bank of England update to append each new day.
- Optionally set filters and a Max results limit.
- Click Start. A default run finishes in under a minute.
- Open the Output tab, then download the dataset or connect it to your tools.
Input Parameters
| Parameter | Type | Required | Default | Description |
|---|---|---|---|---|
startDate | string | No | — | First trading date, YYYY-MM-DD. Leave empty to use the lookback below. |
endDate | string | No | — | Last trading date, YYYY-MM-DD. Leave empty for today. |
lookbackDays | integer | No | 90 | Used when no start date is set. |
newestFirst | boolean | No | true | Return the newest day first. Turn off for chronological order. |
maxItems | integer | No | 0 | Cap on returned rows. Set 0 for no limit. |
deltaMode | boolean | No | false | After the first run with a delta key, return and bill only days not delivered before. |
deltaStateKey | string | No | "default" | Name of the tracked stream. |
proxyConfiguration | object | No | {"useApifyProxy":false} | Optional proxy. The sources work without one. |
Output Data
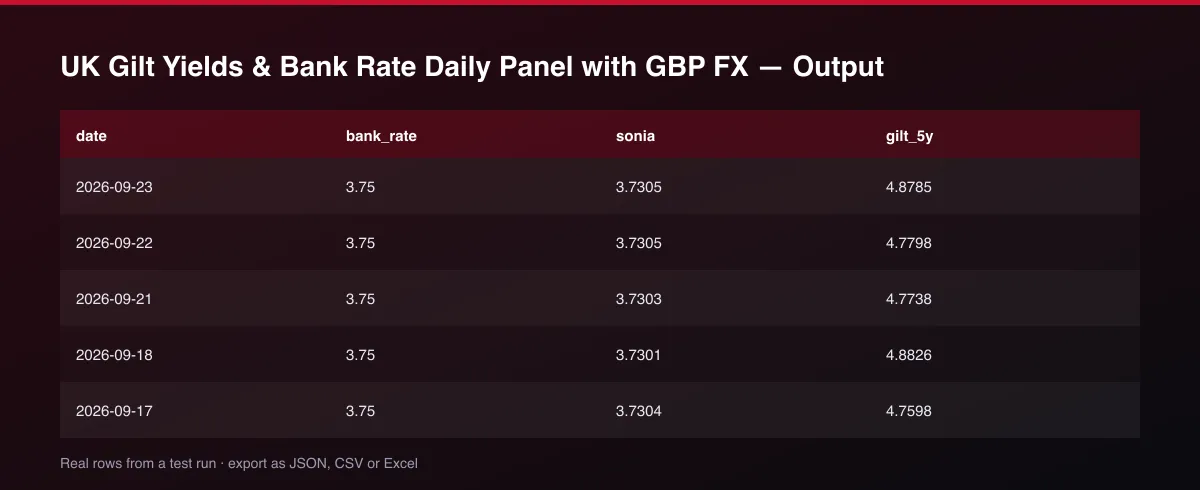
bank_rate and sonia are percent. gilt_* are nominal par yields in percent. breakeven_10y is the 10 year nominal minus real zero-coupon yield. spread_*_bps are yield differences in basis points and curve_regime is inverted (10s5s below 0), flat (below 25 bps) or normal. gilt_10y_over_bank_rate_bps shows how far the 10 year gilt sits above policy. change_* are 1-day changes and gilt_10y_percentile_1y ranks the 10 year yield over the last 252 trading days.
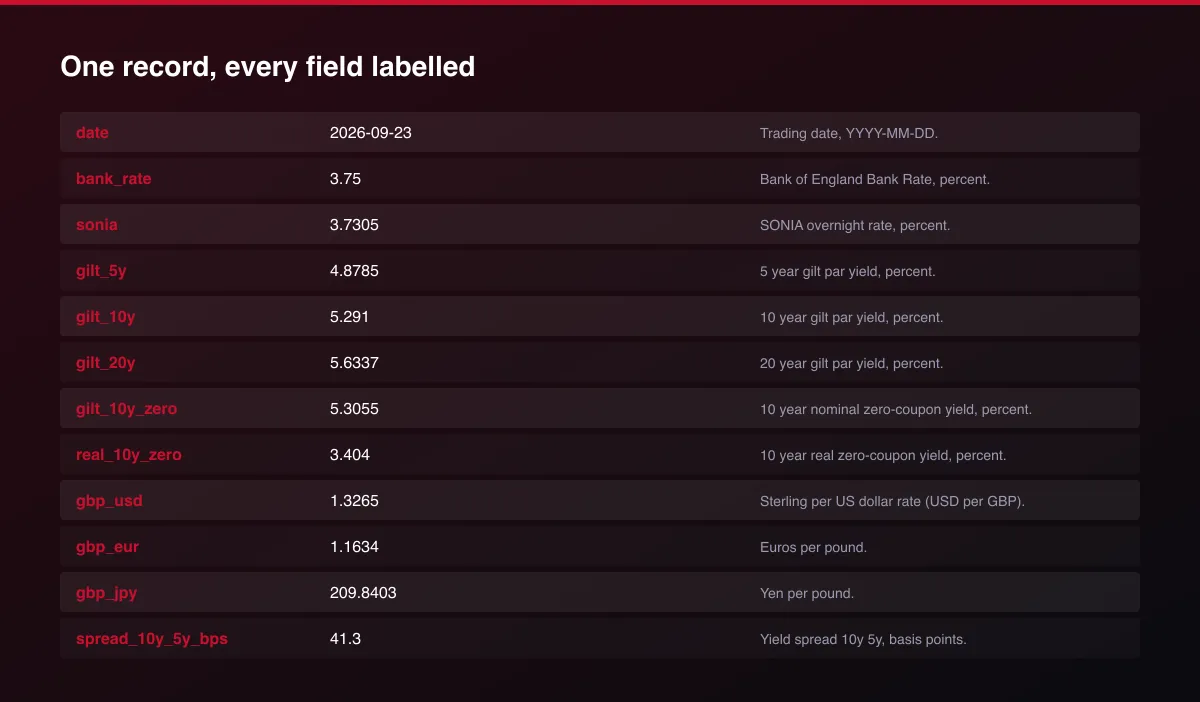
A real dataset item:
How to read and use the results
- Read curve_regime and spread_10y_5y_bps for the gilt curve slope.
- Compare gilt_10y with bank_rate to see market expectations against policy.
- Check breakeven_10y for inflation expectations.
- Use gilt_10y_percentile_1y to compare with the past year.
- Join on date to your own price data.
- Schedule with delta mode to append each new day.
Usage Examples
Last 90 days
Full history for a model
Only new days, for a daily schedule
Tips for Best Results
- Join on the date column; markets are closed on weekends and holidays, so those dates have no row.
- Run the Actor once for the whole history, then schedule it daily with delta mode.
- Use the percentile fields rather than raw levels to compare conditions across years.
- Curve inversion is a slow signal; combine it with faster features such as daily changes.
- Bank Rate changes are visible in change_bank_rate_bps; use them to mark policy days.
- Default is 5 results for a fast test. Set the max to 0 to return everything available.
Reliability by mode
| Mode | Status | Needs login or key? | Notes |
|---|---|---|---|
| Bank Rate, SONIA, gilt yields | ✅ | No | Published by the Bank of England. |
| Breakeven inflation (10 year) | ✅ | No | From the nominal and real zero-coupon curves. |
| GBP exchange rates | ✅ | No | Bank of England spot rates. |
| Intraday or real-time values | ❌ | - | End-of-day only. |
✅ works as described, 🟡 works with caveats, ❌ not supported.
Only new records (delta mode)
Turn on Only new trading days (delta mode) and set a Delta key. The first run returns the whole range; later runs return, and bill, only trading days not delivered before.
Known Limitations
- Values are end-of-day and appear after the Bank of England publishes them, so the newest day can be missing.
- Gilt yields are par and zero-coupon curve estimates, not tradable prices.
- The real yield and breakeven series cover the 10 year point only.
- The percentile uses the trailing 252 trading days and is empty until enough history exists.
- This is information, not financial advice.
Integrations
Run it from the Apify API, on a schedule, or from a webhook. Send results straight to Google Sheets, Make, Zapier, Slack or your own database with Apify's built-in integrations.
Export Formats
Download the dataset as JSON, CSV, Excel, XML, HTML table or RSS from the Output tab or the API.
Frequently Asked Questions
Where does the data come from?
The Bank of England Statistical Interactive Database, which publishes these series for free.
How far back does it go?
Bank Rate and gilt yields go back decades; each series starts at its own publication date.
Does it need an API key or account?
No.
Can I get intraday data?
No, the data is end-of-day.
Why is a value empty?
The series did not exist on that date, or the source has not published that day yet.
Am I charged for empty days?
No, only for rows returned.
Do I need an account or login?
No. The Actor reads public Bank of England data and needs no account or API key.
Am I charged for failed runs or empty results?
You are only charged for results that are actually written to the dataset.
Can I run it on a schedule?
Yes. Create a Task with your input and add a schedule in Apify Console. With monitor mode on, each scheduled run returns only what changed since the previous one.
Changelog
- 2026-09-27: First release.
Enterprise and custom work
Need higher volumes, a custom output schema, dedicated scheduling or a no-breaking-changes commitment for a production pipeline? Open an issue on the Actor page and describe your use case. Bulk terms and custom builds are available.
Support
Questions or a missing field? Open an issue from the Issues tab on this Actor's page and it will be looked at.
Legal / Responsible Use
This Actor reads publicly published Bank of England data. You are responsible for how you use the data. It is not financial advice and not affiliated with the Bank of England.


