

CFTC COT Enhanced — Position Velocity & Percentile Tracker
Pricing
from $150.00 / 1,000 cot records
CFTC COT Enhanced — Position Velocity & Percentile Tracker
Weekly CFTC Commitment of Traders with the percentile + velocity overlay every commodity desk builds in Excel: net position, 3-yr percentile, week-over-week velocity for managed money, swap dealers, commercials, non-reportables. Legacy, disaggregated, TFF families. From publicreporting.cftc.gov.
Pricing
from $150.00 / 1,000 cot records
Rating
0.0
(0)
Developer
NexGenData
Maintained by CommunityActor stats
0
Bookmarked
6
Total users
0
Monthly active users
14 hours ago
Last modified
Categories
Share
📈 CFTC COT Enhanced — Position Velocity & Percentile Tracker
The percentile-and-velocity overlay every commodity desk builds in Excel — sold as a clean weekly API feed. Pulls the CFTC Commitment of Traders (COT) report straight from publicreporting.cftc.gov, then computes net position, 3-year percentile rank, and week-over-week position velocity for every category your desk cares about: managed money, swap dealers, commercials, and non-reportables.
Raw COT JSON is free. The work that turns it into a tradable signal — net-position normalization across long/short/spread fields, 3-year rolling percentile rank vs the trailing 156 weeks, week-over-week velocity calc, and consistent schema across the legacy / disaggregated / financial (TFF) report families — is the value this actor packages. One run, one dataset, one consistent shape.
📊 Sample Output
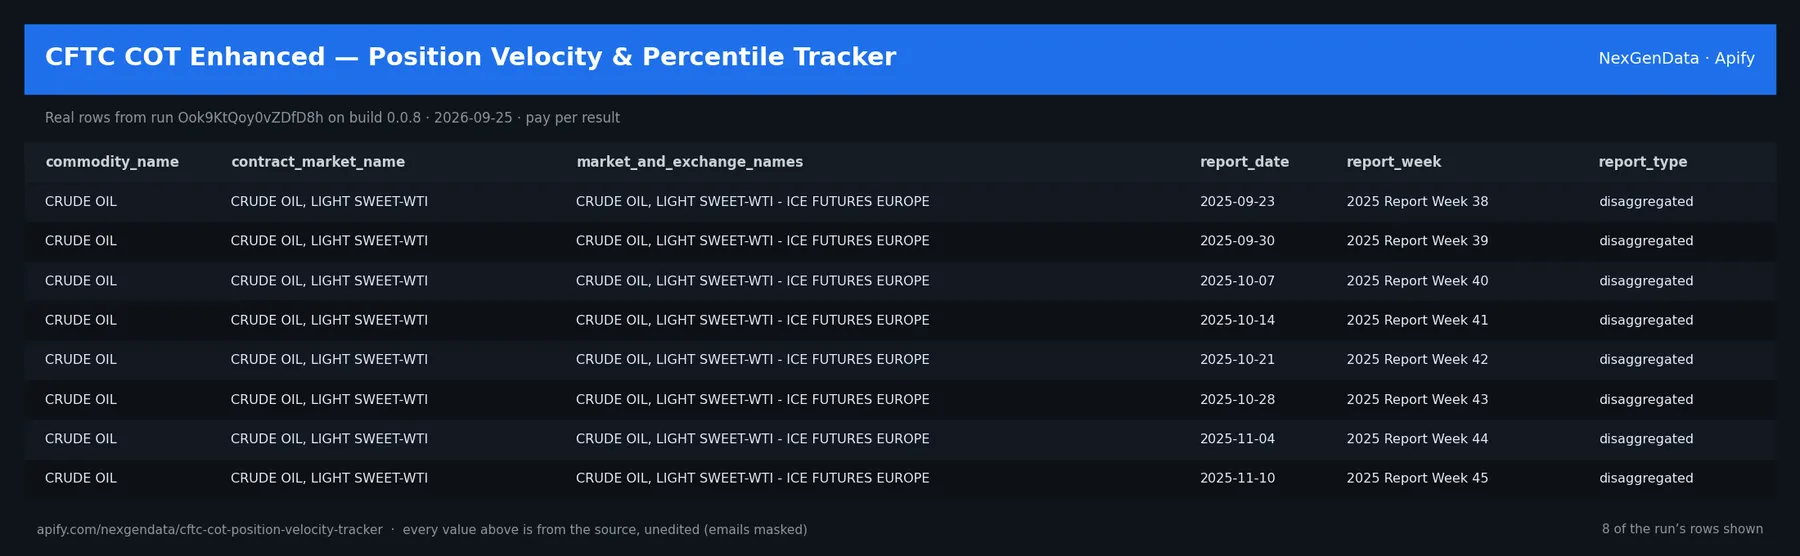
commodity_name | contract_market_name | contract_code | market_and_exchange_names | report_date | report_week |
|---|---|---|---|---|---|
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-09-23 | 2025 Report Week 38 |
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-09-30 | 2025 Report Week 39 |
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-10-07 | 2025 Report Week 40 |
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-10-14 | 2025 Report Week 41 |
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-10-21 | 2025 Report Week 42 |
| CRUDE OIL | CRUDE OIL, LIGHT SWEET-WTI | 067411 | CRUDE OIL, LIGHT SWEET-WTI - ICE FUTURES EUROPE | 2025-10-28 | 2025 Report Week 43 |
Real rows from run Ook9KtQoy0vZDfD8h on build 0.0.8 (2026-09-25), unedited apart from masked emails/phones and shortened long text; fields the source does not publish are empty.
🔧 Input reference
| Field | Type | Default | What it does |
|---|---|---|---|
commodity | string | "WTI CRUDE OIL" | Which CFTC futures market to pull positioning history for. Matching is case-insensitive and runs in this order: (1) exact match on contract_market_name (e.g. `CRUDE OIL, LIGHT S… |
report_type | string (legacy, disaggregated, financial) | "disaggregated" | Which CFTC COT report family to query. legacy = the classic Commercial / Non-Commercial / Non-Reportable breakdown (every futures contract, all commodity groups). `disaggregated… |
weeks_back | integer | 52 | Number of weekly COT reports (most recent first) to emit per (contract × category). Minimum 1, maximum 260 (= 5 years of weekly history). Default = 52 (one year). The actor ALWAYS… |
category | string (managed_money, swap_dealers, commercials, non_reportable, all) | "all" | Which trader bucket to emit positions for. all = emit one row per category that the chosen report_type exposes (5 categories for disaggregated/financial, 3 for legacy). `managed… |
max_records | integer | 100 | Hard ceiling on dataset rows emitted across all (contract × category × week) combinations. Default = 100 (good for one commodity × one category × 52 weeks, or one commodity × 5 ca… |
🧾 JSON sample record
One real record from run Ook9KtQoy0vZDfD8h (emails/phones masked, long text shortened):
💰 Pricing
| Event | Price (USD) | When it is charged |
|---|---|---|
Actor Start (apify-actor-start) | $0.005 | Charged when the Actor starts running. Number of events charged depends on Actor memory (one event per GB, minimum one event). |
COT record (cot-record) | $0.15 | Per week-commodity-category record with percentile + velocity overlay |
Pay-per-event: you pay only for what the run delivers. A run that delivers nothing bills no result events (only the actor-start event, when the actor defines one). Example: a run that delivers 100 results costs 100 × $0.15 = $15.00 plus the start fee.
🔗 Related Actors
More from the NexGenData US government, courts & regulators family:
- CFPB HMDA Mortgage Lending Records API
- CFTC Enforcement Actions Tracker — Case Records API
- CISA KEV + EPSS Vulnerability Intelligence Tracker
- Colorado Business Entity Search — CO Registry Lookup API
48 more in this family on the NexGenData Store page.
What you get
- One row per (contract × category × week) with
commodity_name,contract_market_name,contract_code,report_date,category,long_positions,short_positions,spread_positions,net_position,open_interest_all,percentile_3yr,velocity_week_over_week_pct. - All three CFTC report families.
legacy(Commercial / Non-Commercial / Non-Reportable for every futures contract),disaggregated(Managed Money / Swap Dealers / Producer-Merchant / Other Reportables for energy, metals, ag), andfinancial/ TFF (Asset Manager / Leveraged Funds / Dealer / Other for rates, FX, equity indices). - 3-year percentile rank. For each emitted week, the actor computes the percentile of the current net position vs the trailing 156 weeks for the same contract + category.
managed_moneylong-position percentile of 87 on WTI = positioning is heavier than 87% of the trailing 3-year history. - Week-over-week velocity. Signed percentage change in net position vs the prior week, with absolute-value denominator so the metric stays comparable across long-heavy and short-heavy regimes.
- Flexible commodity matching. Pass an exact
contract_market_name(e.g.CRUDE OIL, LIGHT SWEET-WTI) for a tight single-contract pull, or a fuzzier commodity term likeGOLD,NATURAL GAS,CORN,SOYBEANSfor a multi-contract sweep. - No anti-bot risk. The CFTC Socrata API is an explicit public-data endpoint with no auth, no rate-limit auth, and stable JSON.
User-Agent: NexGenData CFTC COT Actor hello@thenextgennexus.comper the CFTC fair-access convention.
Use cases
- Commodity trader / energy desk. Daily check for "are managed money WTI longs at a >90th percentile vs trailing 3 years?" — historically the cleanest mean-reversion signal in crude oil. Pair the velocity column with the percentile to catch the moment the smart money starts unwinding extreme positioning.
- Macro hedge fund analyst. Cross-commodity positioning regime tracker — pull
report_type=financialfor rates and FX TFF,disaggregatedfor energy and ag, and pipe them into your factor model. The percentile + velocity overlay replaces the manual Excel pivot every analyst rebuilds quarterly. - Ag merchant / corn-soy hedger. Weekly snapshot of where commercial hedgers and managed money sit on CBOT corn, wheat, soybeans + the basis for futures-vs-cash decisions. The 3-year percentile is the canonical anchor used by every grain elevator risk desk.
Sample input
Tight single-category single-commodity run:
Financial (TFF) report for the S&P 500 E-Mini:
Sample output
Each emitted record is one dataset row. The percentile is in 0–100 and is null when there are fewer than 4 trailing reference weeks for that contract × category (typical only for very recently listed contracts). The velocity is null when the prior week's net position is unavailable or zero.
How the data flows
| Stage | What happens |
|---|---|
| 1. Fetch | One Socrata GET /resource/{dataset_id}.json?$where=…&$order=report_date DESC&$limit={weeks_back + 156} against the chosen report family (6dca-aqww legacy, 72hh-3qpy disaggregated, gpe5-46if financial / TFF). |
| 2. Group | Rows are bucketed by contract_market_name so multi-contract commodity queries (e.g. CRUDE OIL matches WTI + Brent + heating-oil cross-spreads) get independent percentile / velocity lineages per contract. |
| 3. Normalize | Per category, long / short / spread fields are pulled from the correct columns for that report family (e.g. m_money_positions_long_all for disaggregated managed money, lev_money_positions_long for financial TFF leveraged money). |
| 4. Compute | net_position = long - short. percentile_3yr = classical rank of current net vs the trailing 156 weeks. velocity_week_over_week_pct = signed % change in net with absolute-value denominator. |
| 5. Emit | Most-recent weeks_back rows per (contract × category), capped at max_records. Each emitted record is also charged via cot-record PPE so cost scales linearly with dataset rows. |
🔗 Related Actors
NexGenData publishes a deep finance + regulatory cluster — pair this COT tracker with any of these for end-to-end positioning + filings + enforcement intelligence:
| Actor | What it does |
|---|---|
| SEC EDGAR Search | Full-text EDGAR filing search across every form type — pair with COT positioning to cross-check insider activity vs futures-desk positioning. |
| SEC Form 4 Insider Trading | Daily insider buy/sell filings — the equity-market counterpart to COT futures positioning. |
| SEC Form 13F Holdings Tracker | Quarterly institutional 13F holdings — pair with COT financial (TFF) for a complete view of managed-money positioning across equities and rates. |
| SEC Form 8-K Material Events | Material-event filings — overlay on commodity-name-mentioning issuers to catch supply / earnings shocks before they move COT positioning. |
| SEC Form D Scraper | Reg D private offerings — useful for tracking commodity-fund and CTA capital formation that feeds managed-money positioning. |
| SEC Litigation Releases | Daily SEC enforcement press releases — the regulatory companion to commodity-market positioning intelligence. |
| SEC Schedule 13D/G Activist Tracker | Activist-investor 13D/G filings for cross-referencing with COT positioning in commodity-linked equities. |
About NexGenData
NexGenData publishes a deep catalogue of Apify actors covering financial regulators, IP offices, government registries, sanctions lists, and corporate filings across the US, EU, UK, APAC, and beyond. Engineered for daily compliance pipelines, M&A diligence, and quant research. Every actor links back to an authoritative public source.
Contact: hello@thenextgennexus.com
🔗 Related NexGenData Actors
Part of the NexGenData Financial Markets suite — pair this Actor with:
- ETF Holdings Tracker Constituents, Weights, AUM
- FX Rates Tracker G10 + EM Currency Pairs Spot Data
- Dividend Aristocrats Kings, Achievers, Growth Stocks
- Earnings Calendar Upcoming Earnings + EPS Estimates
- SPAC Tracker Mergers, Redemptions, Trust Values
- US Treasury Yields & Bond Data Curve, 2s10s, Spreads
- Options Unusual Activity Volume, OI, Sweep Tracker
- Corporate Actions Splits, Spinoffs, M&A, Tender Offers


